
Pipeline Construction Market to Exceed $70 billion by 2030 at 6% CAGR, TechnipFMC Holds 7% Market Share
Pipeline Construction Market
Pipeline And Process Services Market Report size
Pipeline Construction Market Share
The Business Research Company’s Pipeline Construction Market Global Market Report 2026 – Market Size, Trends, And Forecast 2026-2035
LONDON, GREATER LONDON, UNITED KINGDOM, October 8, 2026 /EINPresswire.com/ -- The pipeline construction industry is set for notable growth as global infrastructure demands rise, driven by expanding energy needs and urban development. This sector plays a crucial role within the broader Construction and Utility System Construction markets, reflecting its importance in facilitating energy transport and utility distribution worldwide. Let’s explore the current market size, growth trends, regional leaders, and key drivers shaping the pipeline construction market.
Pipeline Construction Market Size and Industry Context
By 2030, the pipeline construction market is expected to surpass $70 billion. This sector forms a significant part of the larger Utility System Construction market, which is projected to reach nearly $987 billion by the same year, with pipeline construction accounting for about 7% of that figure. Looking further up the hierarchy, the overall Construction industry is forecast to hit $21,691 billion by 2030, with pipeline construction representing roughly 0.3% of the total market value.
Request A Free Sample Of The Pipeline Construction Market Report
https://thebusinessresearchcompany.com/sample_request?id=64247658&type=smp&name=Pipeline%20Construction%20Market%20Report%202026&utm_source=EINPresswire&utm_medium=Paid&utm_campaign=Oct_PR
Growth Outlook for the Pipeline Construction Market
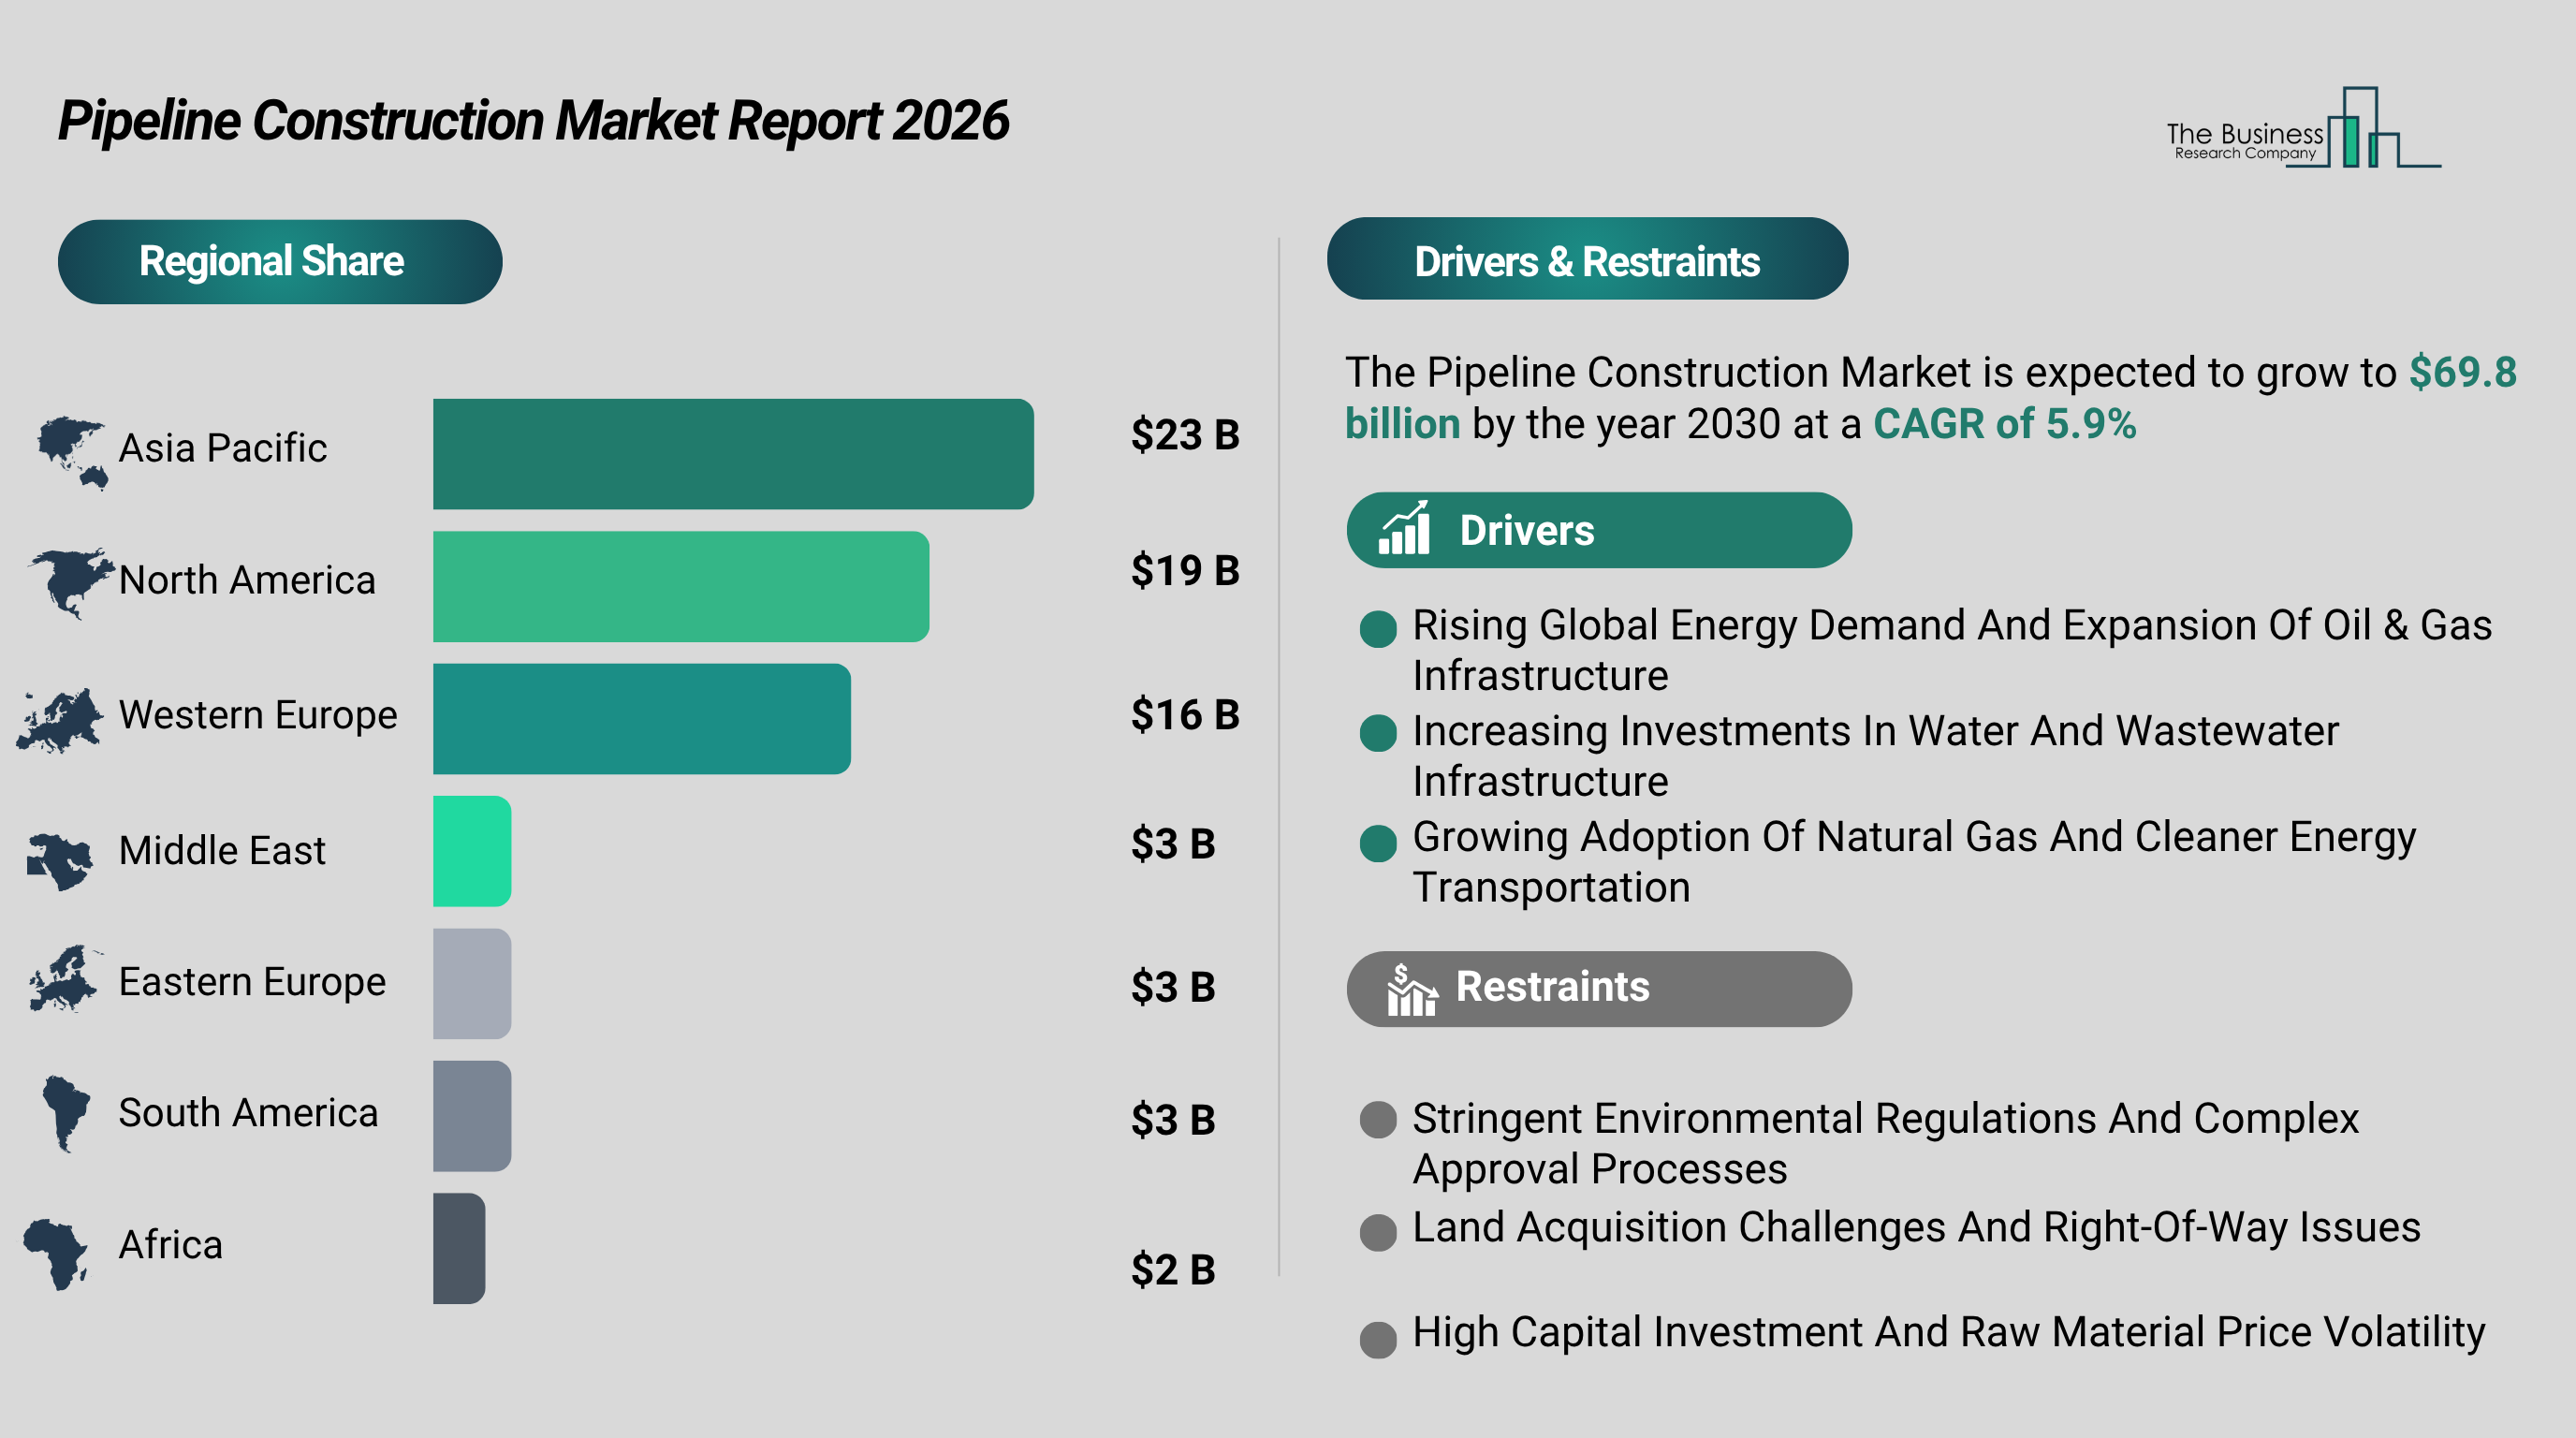
The pipeline construction market is anticipated to maintain a steady compound annual growth rate (CAGR) of 6% as it approaches 2030, indicating robust and consistent expansion fueled by rising infrastructure investments and technological advancements.
Asia-Pacific Leading the Pipeline Construction Market Regionally
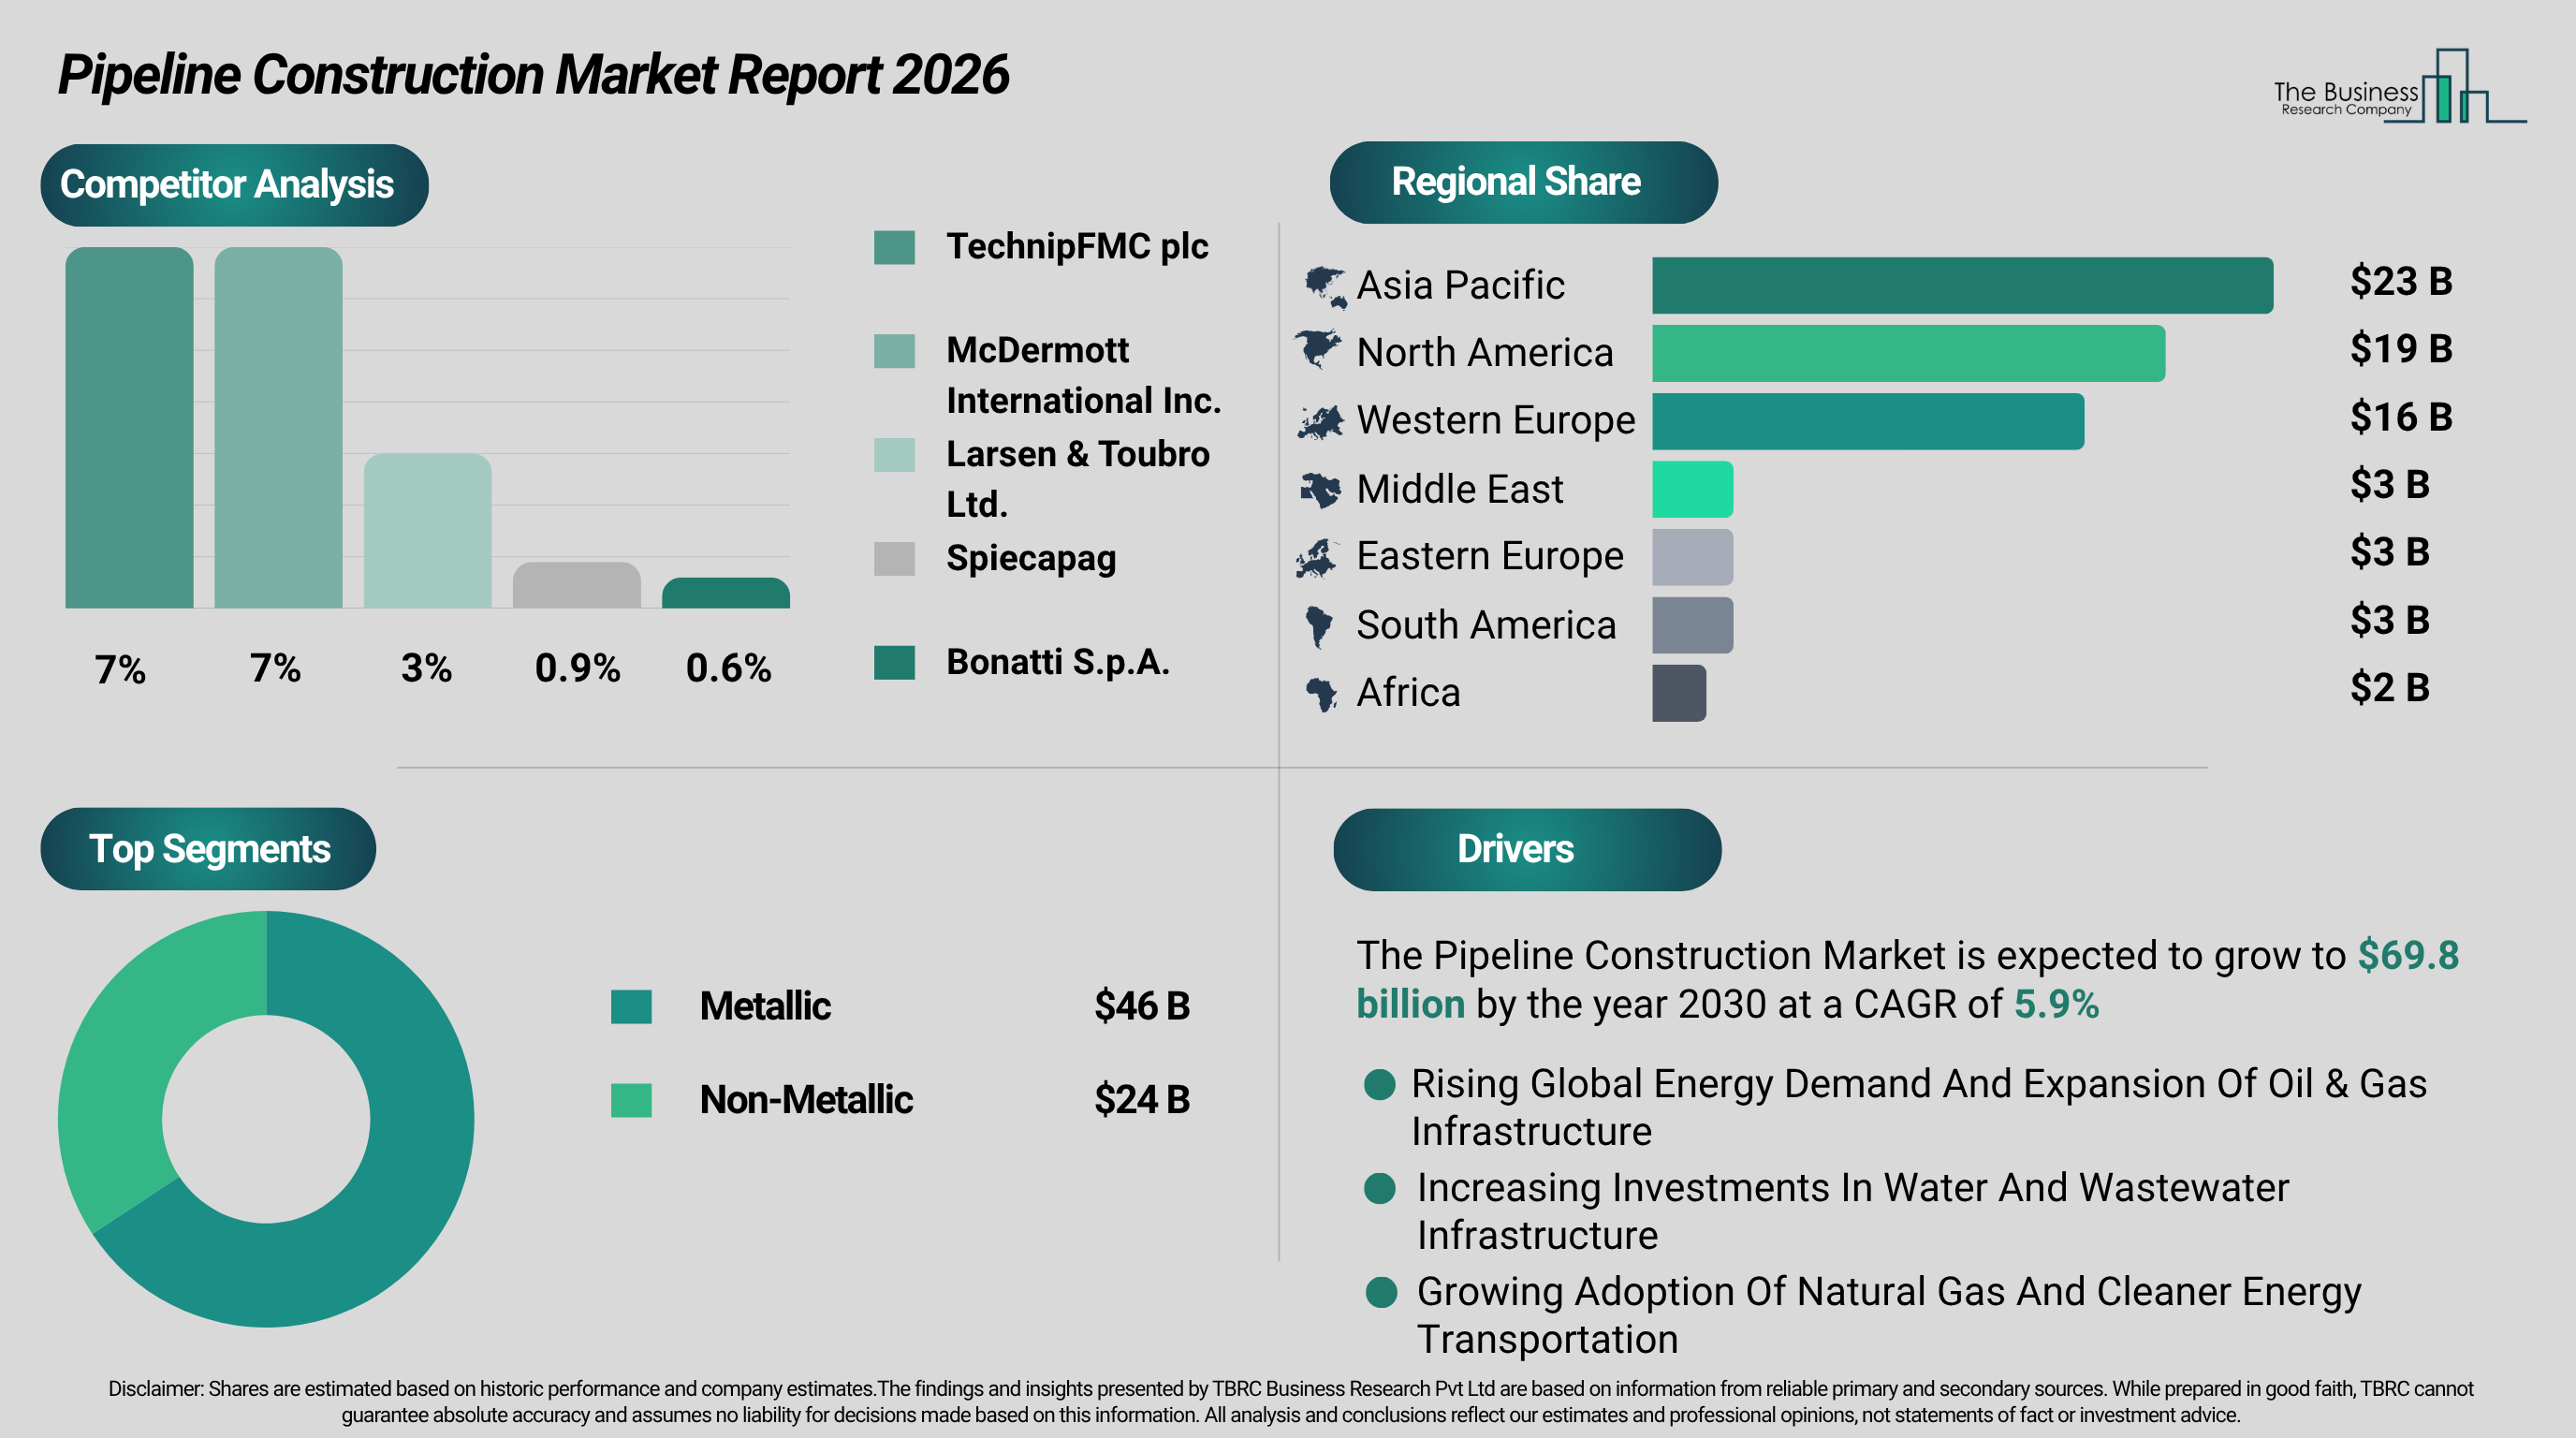
Asia-Pacific is projected to be the largest regional market for pipeline construction in 2030, valued at $23 billion, growing from $18 billion in 2025 at a CAGR of 5%. This growth is underpinned by ongoing investments in cross-border energy transport systems, urban expansion requiring water and utility pipelines, development of new industrial zones, and strong government backing for large-scale infrastructure projects in emerging economies.
Access The Detailed Pipeline Construction Market Report Here
https://thebusinessresearchcompany.com/report/pipeline-construction-global-market-report?utm_source=EINPresswire&utm_medium=Paid&utm_campaign=Oct_PR
United States as the Dominant Country in Pipeline Construction
The United States is set to lead the pipeline construction market by country, with a valuation of $17 billion in 2030, up from $13 billion in 2025, growing at a 5% CAGR. This growth trajectory is supported by the expansion of natural gas transport infrastructure, ongoing pipeline replacement and enlargement programs, and the demand for reliable energy distribution networks that enhance industry efficiency and long-term transmission system resilience.
Segments of the Pipeline Construction Market by Product and Application
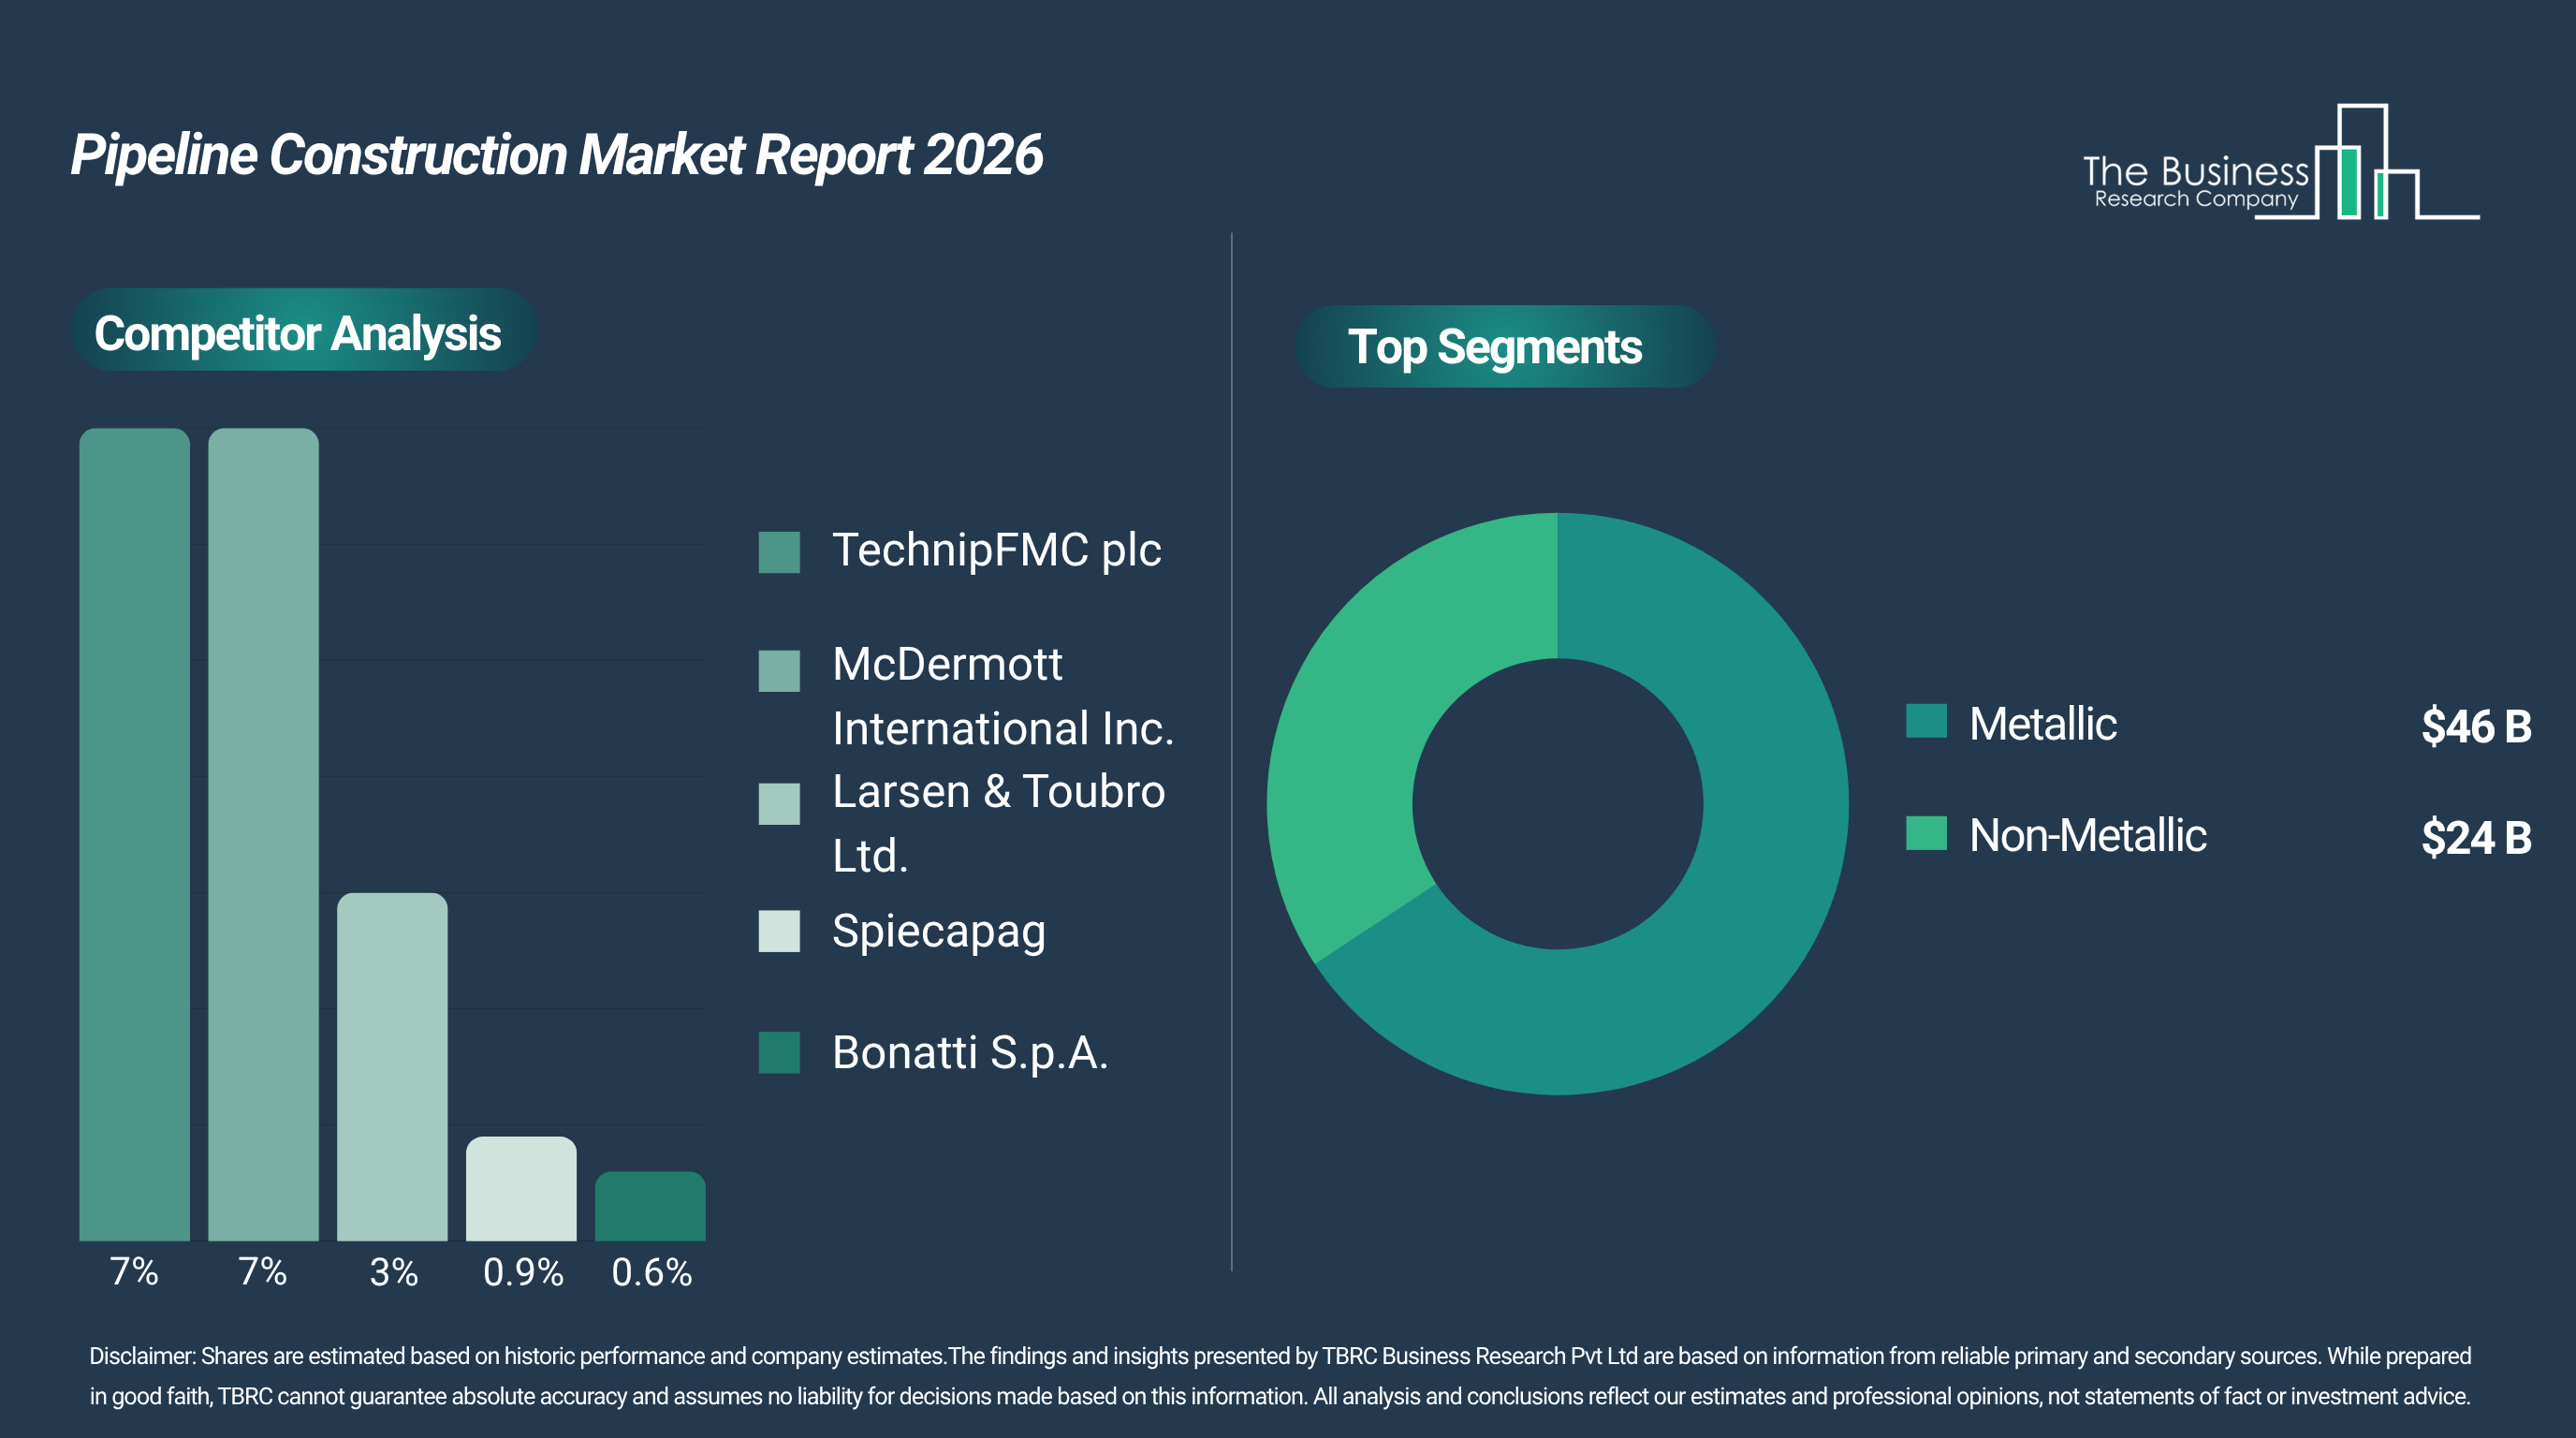
The market divides into metallic and non-metallic pipe types, with metallic pipes expected to dominate, making up 66% of the market or about $46 billion in 2030. The preference for metallic pipelines is driven by their high strength, suitability for long-distance projects, durability under high pressure, corrosion resistance, and extensive use in oil, gas, and industrial transportation.
Other segmentation within the pipeline construction market includes:
- Equipment: valves, pipeline components, metering skids, and compressor stations.
- Operation: transmission versus distribution.
- Application: liquid pipelines and gas pipelines.
- End users: oil and gas, chemical industry, water and wastewater management, energy sector, and other industries.
Key Factors Fueling Pipeline Construction Market Growth
One of the main drivers is the expansion of energy transport infrastructure. Increasing industrial activity, rapid urban growth, and higher energy consumption are pushing governments and energy companies to build extensive transmission networks connecting production sites, refineries, LNG terminals, and distribution hubs. Cross-border pipeline projects and the need to replace outdated lines also add to market momentum, contributing roughly 2.8% to annual growth.
Another significant influence is the rising investment in water and wastewater pipeline infrastructure. Municipalities and governments are upgrading drinking water supplies, wastewater collection systems, irrigation facilities, desalination plants, and recycling operations to serve growing populations and comply with environmental regulations. The replacement of aging underground pipes further stimulates market demand, accounting for about 2.6% annual growth.
A third important driver is the growing adoption of natural gas and cleaner energy transmission. Expanding gas transmission and distribution networks, alongside investments in hydrogen pipelines, renewable natural gas, and carbon capture transport infrastructure, support the transition to greener energy sources. These developments are backed by projects in city gas distribution and industrial gas supply, contributing approximately 2.3% to yearly market growth.
Promising Growth Opportunities in Metallic and Non-Metallic Pipeline Segments
Both metallic and non-metallic pipeline types are expected to offer substantial market opportunities, collectively adding over $17 billion in value between 2025 and 2030. Metallic pipelines alone are projected to grow by $11 billion, with the remaining $6 billion coming from non-metallic segments. Growth drivers include advancements in corrosion-resistant materials, investments in long-distance energy and water pipeline transmission, cutting-edge monitoring and leak detection technologies, and infrastructure development for natural gas, hydrogen, and sustainable water distribution systems.
Competitive Landscape of the Pipeline Construction Market
The market is led by global engineering and construction firms, pipeline infrastructure providers, and specialized energy service contractors. These companies focus on developing innovative pipeline installation methods, automated monitoring systems, corrosion-resistant materials, and effective project management to expand their market share. Compliance with pipeline safety standards, operational reliability, environmental regulations, and the integration of digital asset management systems are essential competitive factors in this space.
Market Leader TechnipFMC plc and Its Role
TechnipFMC plc held the top global market share in 2025 with 7%, specifically through its subsea and surface technologies division. This segment offers advanced pipeline engineering, offshore pipeline installation, and comprehensive project management services that support large-scale energy infrastructure projects, including oil and gas transportation networks.
Market Fragmentation and Competitive Dynamics
In 2025, the top ten companies accounted for 21% of total market revenue, indicating moderate fragmentation. Barriers such as complex engineering demands, strict safety standards, environmental compliance, and specialized construction skills influence competition. Leading firms maintain their positions through diversified capabilities, strong project portfolios, global execution networks, and a commitment to innovation. As demand for energy transport infrastructure grows, strategic alliances, innovative construction technologies, and geographic expansion will be pivotal for strengthening market presence.
Market Shares of Leading Pipeline Construction Companies in 2025
• TechnipFMC plc: 7%
• McDermott International Inc.: 7%
• Larsen & Toubro Ltd.: 3%
• Spiecapag: 1%
• Bonatti S.p.A.: 1%
• Primoris Services Corporation: 1%
• Enka İnşaat ve Sanayi A.Ş.: 1%
• Ledcor Group: 1%
• Barnard Construction Company Inc.: 1%
• Mott MacDonald Group Ltd.: 0.5%
Key Industry Players in the Pipeline Construction Sector
Notable companies in this market include TechnipFMC plc, McDermott International Inc., Larsen & Toubro Ltd., Spiecapag, Bonatti S.p.A., Primoris Services Corporation, Enka İnşaat ve Sanayi A.Ş., Ledcor Group, Barnard Construction Company Inc., Mott MacDonald Group Ltd., TMK Group, Kinder Morgan Inc., Joint Stock Company Transneft, Enterprise Products Partners L.P., Enbridge Inc., CRC-Evans Pipeline International Inc., Cecon Group, CCI Leidingsystemen B.V., Sung IL Sim Co. Ltd., and Gateway Pipeline LLC.
Emerging Competitive Trends in Pipeline Construction
Inter-oceanic energy corridor pipelines are reshaping the market by enhancing energy transport efficiency, increasing capacity utilization, and reducing maritime transit delays. A notable development occurred in September 2025 when The Panama Canal Authority initiated a concession process for a 76-kilometer inter-oceanic energy pipeline connecting Atlantic and Pacific terminals. This pipeline, with a capacity of 2.5 million barrels per day and able to transport propane, butane, and ethane, offers improved logistics, operational efficiency, and energy security.
Strategic Focus Areas for Pipeline Construction Companies
Key priorities include advancing pipeline construction technologies to boost project reliability, adopting innovative methods to optimize costs and efficiency, expanding infrastructure to improve energy connectivity, and integrating digital solutions for better monitoring and automation.
Pipeline Construction Market Supply Chain and Customer Network
Suppliers of raw materials include major steel and coating manufacturers such as Tenaris S.A., Vallourec S.A., Nippon Steel Corporation, ArcelorMittal S.A., Tata Steel Limited, Jindal SAW Limited, United States Steel Corporation, ThyssenKrupp AG, Evraz plc, China Baowu Steel Group Corporation Limited, Nucor Corporation, SSAB AB, Salzgitter AG, JSW Steel Limited, Hyundai Steel Company, POSCO Holdings Inc., Borusan Mannesmann Boru Sanayi ve Ticaret A.Ş., TMK Group, Welspun Corp Limited, Saudi Steel Pipe Company, Shawcor Ltd., PPG Industries, Inc., 3M Company, Axalta Coating Systems Ltd., and Hempel A/S.
Wholesalers and distributors include Ferguson Enterprises, Inc., W.W. Grainger, Inc., Fastenal Company, HD Supply Holdings, Inc., Rexel S.A., Sonepar Group, WESCO International, Inc., Graybar Electric Company, Inc., Applied Industrial Technologies, Inc., Motion Industries, Inc., MSC Industrial Supply Co., Inc., RS Group plc, Würth Group, Global Industrial Company, Inc., SupplyWorks, Inc., Kaman Distribution Group, Hajoca Corporation, Winsupply Inc., Core & Main Inc., Wolseley UK Limited, MRC Global Inc., DNOW Inc., and DistributionNOW, Inc.
Major end users range from large construction and energy corporations such as Bechtel Corporation, Fluor Corporation, Jacobs Solutions Inc., Kiewit Corporation, Saipem S.p.A., Technip Energies N.V., McDermott International Ltd., Petrofac Limited, Larsen & Toubro Limited, China Petroleum Pipeline Engineering Corporation, Primoris Services Corporation, Quanta Services, Inc., MasTec, Inc., Barnard Construction Company, Michels Corporation, Enbridge Inc., Kinder Morgan, Inc., TC Energy Corporation, Williams Companies, Inc., Enterprise Products Partners L.P., Snam S.p.A., National Grid plc, Gasunie N.V., to the Abu Dhabi National Oil Company (ADNOC).
The 2026 edition of our market reports now delivers enhanced analytical coverage through market attractiveness scoring and analysis, total addressable market (TAM) analysis, company scoring matrix graphics and tables, Excel-based forecasting dashboards, market hotspots infographics, key technologies and future trend analysis, plus updated graphics and tables.
About The Business Research Company
The Business Research Company (www.thebusinessresearchcompany.com) is a renowned market intelligence firm specializing in company, market, and consumer research. With over 30,000+ reports spanning 27 industries and more than 60 geographies, their insights draw upon 1.5 million datasets, extensive secondary research, and interviews with industry leaders. They offer a range of tailored research packages such as Market Entry, Competitor Tracking, and Supplier & Distributor packages.
Disclaimer: The information provided by TBRC Business Research Pvt Ltd is gathered in good faith from primary and secondary sources, though accuracy cannot be fully guaranteed. The company disclaims liability for any actions taken based on its findings, which are intended as estimates and opinions rather than definitive facts or investment advice.
Contact Information
The Business Research Company
Americas: +1 310-496-7795
Europe: +44 7882 955267
Asia & Others: +44 7882 955267 / +91 8897263534
Email: marketing@tbrc.info
Follow on LinkedIn: https://in.linkedin.com/company/the-business-research-company"
Oliver Guirdham
The Business Research Company
+44 7882 955267
info@tbrc.info
Visit us on social media:
LinkedIn
Facebook
X
Legal Disclaimer:
EIN Presswire provides this news content "as is" without warranty of any kind. We do not accept any responsibility or liability for the accuracy, content, images, videos, licenses, completeness, legality, or reliability of the information contained in this article. If you have any complaints or copyright issues related to this article, kindly contact the author above.
