
Semiconductor Market Size To Reach $1036.9 Billion By 2030 At A CAGR Of 9.3%
semiconductor_market_report
semiconductor-manufacturing
semiconductor_market_report_regionalmarket
The Business Research Company’s Semiconductor Market Global Market Report 2026 – Market Size, Trends, And Forecast 2026-2035
LONDON, GREATER LONDON , UNITED KINGDOM, October 28, 2026 /EINPresswire.com/ -- The semiconductor industry is rapidly evolving, driven by technological advances and expanding global demand. With key regions investing heavily in manufacturing capabilities and innovation, the market is set for substantial growth over the next decade. Let’s explore the current landscape, emerging drivers, key players, and future outlook within this vital sector.
Asia-Pacific Positioned as the Largest Semiconductor Market by 2030
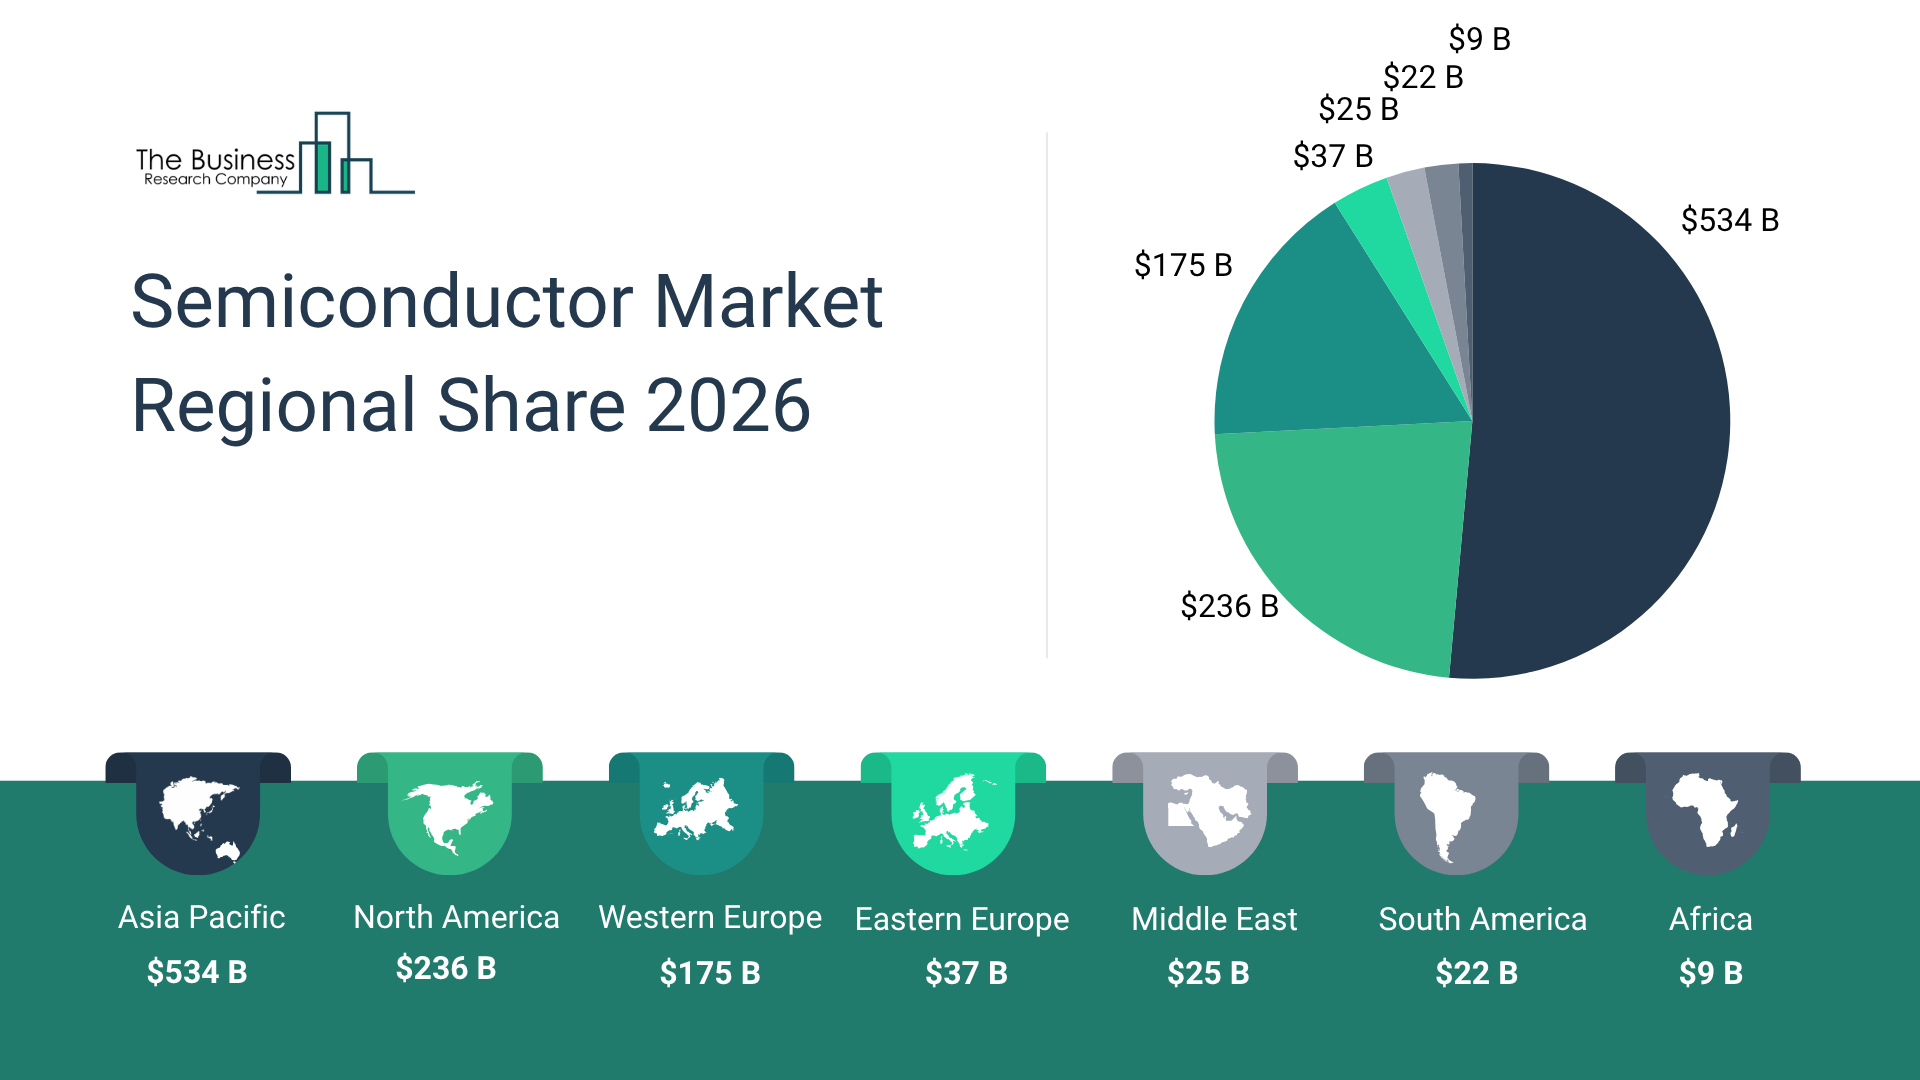
Asia-Pacific is on track to become the leading region in the semiconductor market by 2030, reaching a valuation of $534 billion. This growth follows a rise from $330 billion in 2025 at a compound annual growth rate (CAGR) of 10%. The expansion is largely fueled by increased fabrication capacity in countries like Taiwan, South Korea, China, and Japan. The region’s semiconductor industry thrives on competition among global chipmakers, integrated device manufacturers, foundries, and specialized technology firms focusing on breakthroughs such as advanced fabrication processes, high-performance computing, AI applications, chip miniaturization, energy-efficient design, supply chain strength, and advanced packaging methods.
Request A Free Sample Of The Semiconductor Market Report
https://thebusinessresearchcompany.com/sample_request?id=74232538&type=smp&name=Semiconductor%20Manufacturing%20Equipment%20Market%20Report%202026&utm_source=EINPresswire&utm_medium=Paid&utm_campaign=Oct_PR
Custom ASIC and Mixed-Signal Innovations Revolutionize Semiconductor Capabilities
Innovations in custom ASIC (Application-Specific Integrated Circuit) and mixed-signal chips are transforming the semiconductor market by enabling next-generation electronics that demand high-performance computing, precise sensing, and application-tailored processing. An example of this is MicroVision, Inc., which in July 2026 launched MicroVision Semiconductor, a dedicated division focused on custom ASIC design, mixed-signal integration, photonic sensing, and advanced imaging solutions. This combination enhances processing efficiency and sensory accuracy across sectors including automotive, industrial, defense, autonomous systems, and intelligent perception technologies.
Main Factors Driving the Semiconductor Market Forward Through 2030
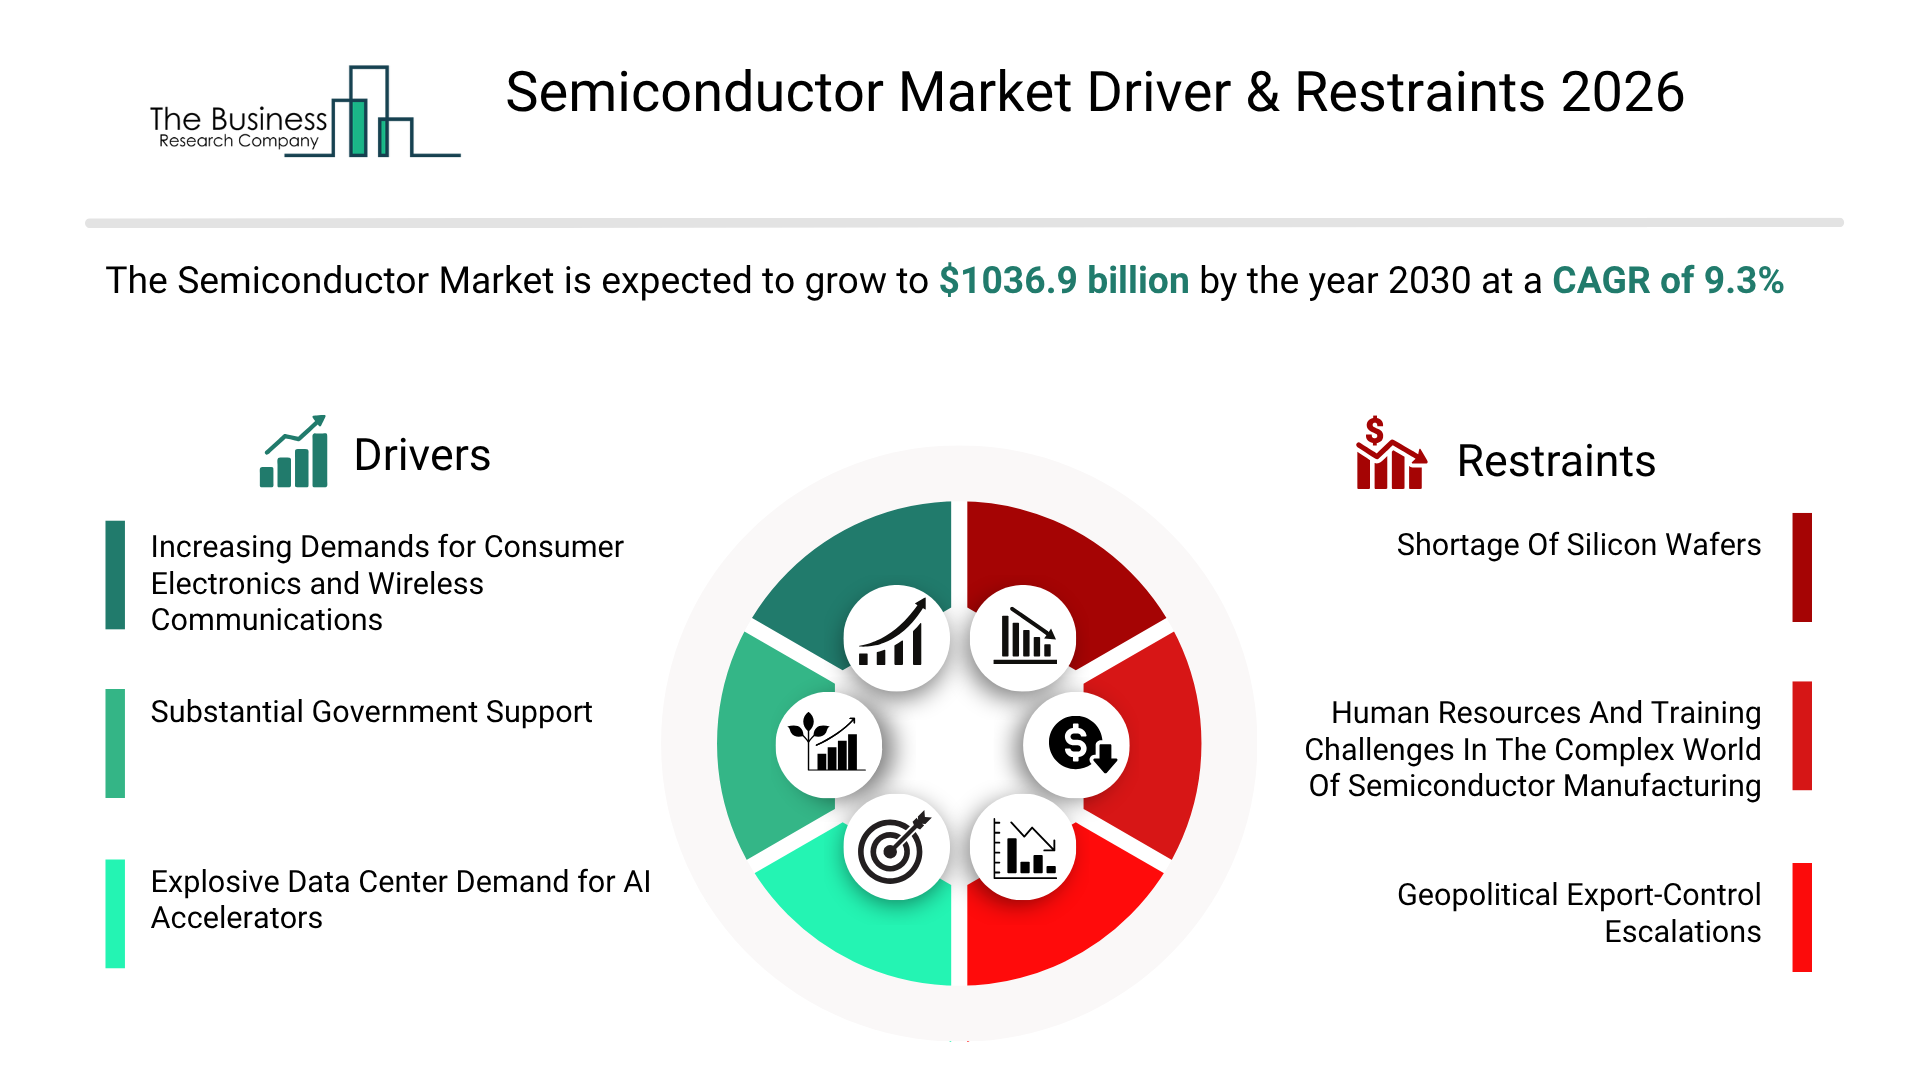
The semiconductor sector’s growth is being driven by three primary forces: increasing demand for consumer electronics and wireless communications, substantial government support for domestic chip production and innovation, and a surge in AI-driven data center infrastructure requiring advanced semiconductor technologies.
Access The Detailed Semiconductor Market Report Here
https://thebusinessresearchcompany.com/report/semiconductor-manufacturing-equipment-global-market-report?utm_source=EINPresswire&utm_medium=Paid&utm_campaign=Oct_PR
Rising Demand for Consumer Electronics and Wireless Technologies
Consumer electronics such as smartphones, tablets, smartwatches, computers, entertainment devices, and home appliances heavily rely on semiconductor chips. Additionally, the trend toward fast charging has boosted demand for silicon carbide (SiC) and gallium nitride (GaN) power semiconductors, which offer greater efficiency and smaller form factors. The deployment of 5G infrastructure also propels need for power semiconductors in routers, modems, base stations, and transmitters. Furthermore, 5G is increasing chip usage in connected vehicles, virtual and augmented reality devices, and high-definition video systems. Supportive policies such as the U.S. CHIPS Act further incentivize investments in advanced semiconductor fabrication. Together, these factors contribute an estimated 2.7% annual market growth.
Robust Government Backing Strengthens Chip Manufacturing Ecosystems
Governments worldwide are intensifying efforts to nurture domestic semiconductor manufacturing, research, and supply chain robustness through funding, grants, and favorable policy frameworks aimed at reducing reliance on imports. For instance, in March 2023, the Canadian government allocated USD 36 million via the Ministry of Innovation, Science and Industry to support Ottawa-based Ranovus Inc. in expanding local semiconductor capabilities. This backing helps mitigate supply chain disruptions, fosters competitiveness, accelerates R&D efforts, facilitates commercialization, and attracts private investments, contributing approximately 2.5% growth annually to the market.
AI Data Centers Spark Massive Demand for Specialized Semiconductor Accelerators
The rise of AI applications has led hyperscale cloud providers to install over 1.5 million GPUs dedicated to AI training, utilizing advanced 4 nm and 5 nm production capacities and resulting in substrate lead times exceeding 40 weeks. GPUs currently dominate the accelerator space, but the shift from AI training to inference increases demand for energy-efficient, low-precision processors and opens opportunities for ASICs designed for specific AI workloads. Additionally, demand for high-bandwidth memory, such as HBM3E stacks, has surged to support trillion-parameter models. The hardware replacement cycle for AI infrastructure has shortened significantly, from about five years to three. This trend is expected to add around 2.2% annual growth to the semiconductor market.
Semiconductor Market Projected to Surpass $1 Trillion, Making Up Majority of Its Parent Industry
By 2030, the semiconductor market is anticipated to exceed $1,037 billion in value. It accounts for roughly 62% of its broader parent industry, termed Semiconductor And Other Electronic Components, which is projected to reach approximately $1,670 billion. Within the greater Electrical And Electronics industry, expected to total $5,579 billion by 2030, semiconductors will represent close to 19% of the overall market. The sector is forecasted to grow at a 9% CAGR through 2030.
Leading Asia-Pacific Region and China’s Dominance in Semiconductor Market
Asia-Pacific’s semiconductor market is set to lead globally with $534 billion in 2030, growing from $330 billion in 2025 at a 10% CAGR. Key factors include expanded fabrication capacity in Taiwan, South Korea, China, and Japan; investments in advanced chip packaging and wafer production; rising demand from consumer electronics and industrial automation; strong government incentives; and rapid adoption of AI, edge computing, and Internet of Things (IoT) devices. Among countries, China is projected to be the top market, valued at $275 billion in 2030, up from $175 billion in 2025 at the same 10% CAGR. Growth drivers include domestic integrated circuit design and manufacturing investments, increasing semiconductor equipment and material output, chip supply chain localization for technological autonomy, and demand linked to electric vehicles, renewable energy, smart manufacturing, and ongoing development in high-performance computing and memory chips.
Product Type Segment “Others” Expected to Hold the Largest Market Share by 2030
Within the semiconductor market, product categories include logic devices, microprocessor units (MPU), power devices, microcontroller units (MCU), analog integrated circuits (IC), memory devices, sensors, discrete power devices, and an “others” segment. By 2030, the “others” category will be the largest segment, capturing 35% of the market or $364 billion. This segment benefits from growing demand for application-specific integrated circuits, custom chips, connectivity and interface components in advanced electronics, radio frequency and mixed-signal parts for wireless applications, optoelectronic and photonic devices in industrial and telecom sectors, continuous innovation in specialized chips for emerging digital functions, and embedded components in next-generation smart devices.
Technology Node, Application, and End-User Segmentation in the Semiconductor Market
The semiconductor market is divided by technology node into categories such as 10 nm and below, 11 to 28 nm, 29 to 65 nm, above 65 nm, and other nodes. Application segments include consumer electronics, automotive, industrial, telecommunications, data centers and computing, healthcare, aerospace and defense, among others. Similarly, end-users encompass consumer electronics, automotive, industrial, telecommunications, healthcare, aerospace and defense sectors, and additional areas.
NVIDIA Tops the Semiconductor Sector in Global Sales
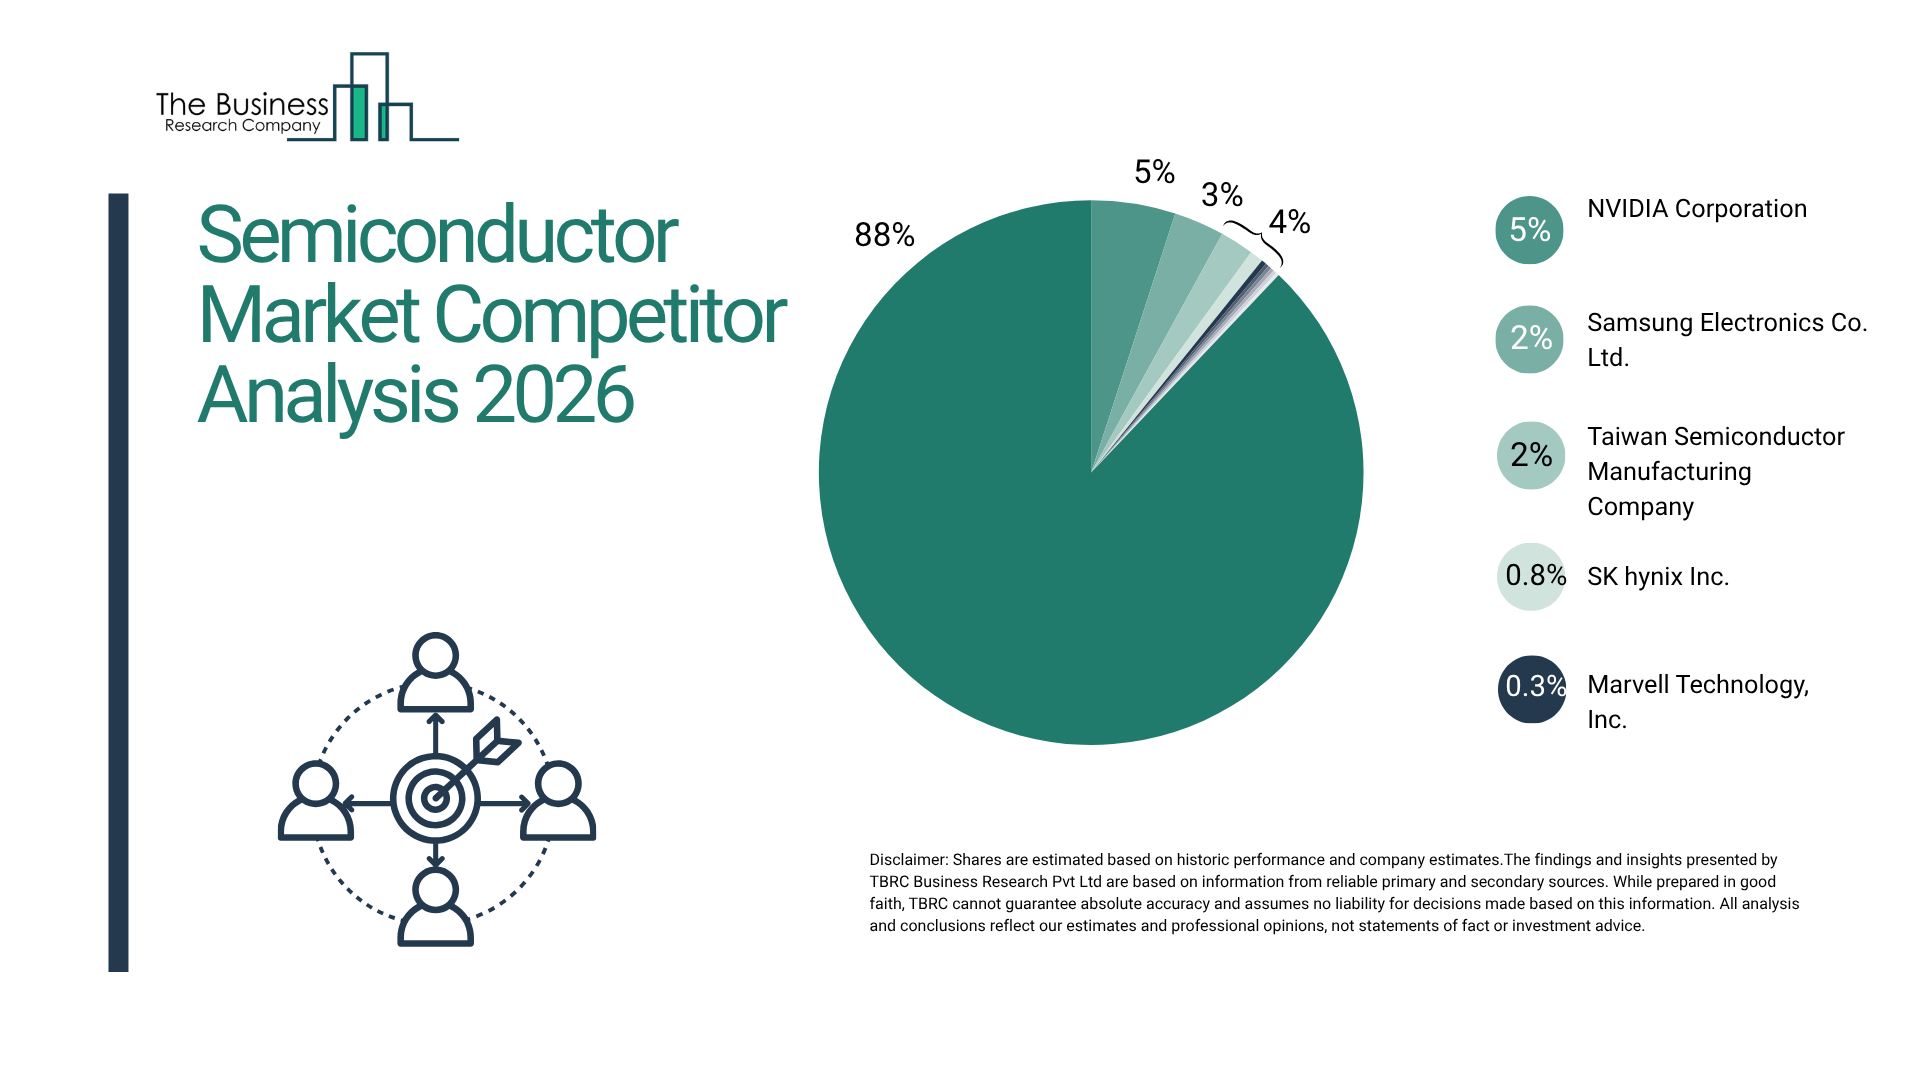
In 2025, NVIDIA Corporation ranked first in worldwide semiconductor sales, capturing a 5% market share. Its compute and networking division directly contributes to the semiconductor market by supplying graphics processing units (GPUs), AI accelerators, high-performance computing chips, and networking semiconductors tailored for AI workloads, data centers, gaming, autonomous systems, and emerging computing platforms.
Prominent Players Leading the Semiconductor Market
Key companies actively shaping the semiconductor industry include NVIDIA Corporation, Samsung Electronics Co. Ltd., Taiwan Semiconductor Manufacturing Company, SK hynix Inc., Marvell Technology, Inc., Qualcomm Incorporated, United Microelectronics Corporation, Broadcom Inc., Micron Technology, Inc., Advanced Micro Devices, Inc., Intel Corporation, ASE Technology Holding Co., Ltd., Microchip Technology Incorporated, ON Semiconductor Corporation, Renesas Electronics Corporation, MediaTek Inc., Texas Instruments Incorporated, Semiconductor Manufacturing International Corporation, Analog Devices, Inc., Kioxia Holdings Corporation, GlobalFoundries Inc., Infineon Technologies AG, NXP Semiconductors N.V., Tower Semiconductor Ltd., and STMicroelectronics N.V.
Degree of Fragmentation Among Top Semiconductor Vendors
The semiconductor market is moderately fragmented, with the top ten companies accounting for only 12% of total revenue in 2025. This fragmentation reflects substantial technological and capital entry barriers, including complex manufacturing processes, sizable investments in advanced fabrication facilities, intellectual property challenges, intricate supply chains, and persistent innovation demands. Market leaders maintain their positions through broad product portfolios, extensive manufacturing capabilities, substantial R&D budgets, strategic alliances, and global distribution networks. As demand grows for AI processors, high-performance computing, advanced memory solutions, and next-generation applications, ongoing technological advancements, capacity expansions, and regional manufacturing initiatives are expected to strengthen these companies’ market shares.
Market Shares of Leading Semiconductor Companies in 2025
The ten leading firms and their respective market shares are:
• NVIDIA Corporation (5%)
• Samsung Electronics Co. Ltd. (3%)
• Taiwan Semiconductor Manufacturing Company (2%)
• SK hynix Inc. (1%)
• Marvell Technology, Inc. (0.3%)
• Qualcomm Incorporated (0.3%)
• United Microelectronics Corporation (0.2%)
• Broadcom Inc. (0.2%)
• Micron Technology, Inc. (0.2%)
• Advanced Micro Devices, Inc. (0.2%)
Competitive Strategies Influencing the Semiconductor Industry
The competitive landscape is shaped by efforts to advance semiconductor technologies for better processing power and energy efficiency, adoption of new materials to enhance chip reliability and performance, expansion of production capacity to improve supply chain resilience, and integration of AI semiconductor solutions to support computing and automation.
Key Suppliers, Distributors, and End Users in the Semiconductor Ecosystem
The semiconductor supply chain involves major raw material providers like Shin-Etsu Chemical Co., Ltd., SUMCO Corporation, GlobalWafers Co., Ltd., Siltronic AG, SK Siltron Co., Ltd., Soitec S.A., Air Liquide S.A., Linde plc, BASF SE, Merck KGaA, Entegris, Inc., DuPont de Nemours, Inc., JSR Corporation, Tokyo Ohka Kogyo Co., Ltd., Dow Inc., Cabot Microelectronics Corporation, Resonac Holdings Corporation, Fujifilm Holdings Corporation, Versum Materials, Inc., Kanto Chemical Co., Inc., Mitsubishi Chemical Group Corporation, Henkel AG & Co. KGaA, Tosoh Corporation, Umicore N.V., and Materion Corporation.
Wholesalers and distributors include firms such as Arrow Electronics, Inc., Avnet, Inc., WPG Holdings Limited, Digi-Key Electronics, Mouser Electronics, Inc., TTI, Inc., Future Electronics Inc., RS Group plc, Newark Electronics, Allied Electronics & Automation, Rutronik Elektronische Bauelemente GmbH, Macnica, Inc., Marubeni Information Systems Co., Ltd., Rochester Electronics, LLC, Fusion Worldwide, Inc., Smith & Associates, Inc., Richardson RFPD, Master Electronics, Inc., PEI-Genesis, Inc., Sager Electronics, Inc., Heilind Electronics, Inc., Powell Electronics, Inc., element14, Inc., Chip One Stop, Inc., and CoreStaff Co., Ltd.
Major end-users encompass Taiwan Semiconductor Manufacturing Company Limited, Samsung Electronics Co., Ltd., Intel Corporation, NVIDIA Corporation, Qualcomm Incorporated, Broadcom Inc., Micron Technology, Inc., Advanced Micro Devices, Inc., Texas Instruments Incorporated, STMicroelectronics N.V., Infineon Technologies AG, NXP Semiconductors N.V., Renesas Electronics Corporation, Analog Devices, Inc., MediaTek Inc., Marvell Technology, Inc., ON Semiconductor Corporation, Microchip Technology Incorporated, Kioxia Corporation, SK Hynix Inc., Sony Semiconductor Solutions Corporation, Toshiba Electronic Devices & Storage Corporation, ASE Technology Holding Co., Ltd., Amkor Technology, Inc., and United Microelectronics Corporation.
Memory and Others Product Categories Expected to Add Over $370 Billion by 2030
By 2030, all semiconductor product segments, including logic devices, MPU, power devices, MCU, analog IC, memory devices, sensors, discrete power devices, and others, are forecasted to collectively generate more than $372 billion in additional market value. Between 2025 and 2030, estimated growth by segment includes logic devices increasing by $8 billion, MPU by $32 billion, power devices by $24 billion, MCU by $30 billion, analog IC by $50 billion, memory devices by $64 billion, sensors by $44 billion, discrete power devices by $9 billion, and others by $111 billion. This expansion is supported by advances in AI and high-performance computing chips, energy-efficient solutions for electric vehicles and renewable energy, broader adoption of connected devices and edge computing, continuous improvements in chip architecture and fabrication processes, and investments in next-generation computing and communication infrastructure—all reflecting the fast-paced digital transformation across computing, communication, automotive, and industrial electronics sectors.
New strategic additions in our 2026 market reports include market attractiveness scoring and analysis, total addressable market (TAM) analysis, company scoring matrix graphics and tables, Excel-based forecasting dashboards, market hotspots infographics, key technologies and future trend analysis, along with updated graphics and tables.
Learn More About The Business Research Company
The Business Research Company (www.thebusinessresearchcompany.com) is a leading market intelligence firm renowned for its expertise in company, market, and consumer research. We have published over 30,000+ reports across 27 industries and 60+ geographies. Our research is powered by 1,500,000 datasets, extensive secondary research, and exclusive insights from interviews with industry leaders.
We provide continuous and custom research services, offering a range of specialized packages tailored to your needs, including Market Entry Research Package, Competitor Tracking Package, Supplier & Distributor Package and much more.
Disclaimer: Please note that the findings, conclusions and recommendations that TBRC Business Research Pvt Ltd delivers are based on information gathered in good faith from both primary and secondary sources, whose accuracy we are not always in a position to guarantee. As such TBRC Business Research Pvt Ltd can accept no liability whatever for actions taken based on any information that may subsequently prove to be incorrect. Analysis and findings included in TBRC reports and presentations are our estimates, opinions and are not intended as statements of fact or investment guidance.
Contact Us:
The Business Research Company
Americas +1 310-496-7795
Europe +44 7882 955267
Asia & Others +44 7882 955267 & +91 8897263534
Email: marketing@tbrc.info
Follow Us On:
LinkedIn: https://in.linkedin.com/company/the-business-research-company.
Oliver Guirdham
The Business Research Company
+44 7882 955267
info@tbrc.info
Visit us on social media:
LinkedIn
Facebook
X
Legal Disclaimer:
EIN Presswire provides this news content "as is" without warranty of any kind. We do not accept any responsibility or liability for the accuracy, content, images, videos, licenses, completeness, legality, or reliability of the information contained in this article. If you have any complaints or copyright issues related to this article, kindly contact the author above.
